Who We Are and Why
A team of researchers who believed rigorous risk estimation deserved a wider audience
Our team grew from a shared observation: the methods used by quantitative researchers to estimate equity, credit, and volatility risk premiums were rarely accessible outside specialist academic circles. Distribution-free statistical techniques — the kind that do not rely on parametric model assumptions — were producing more honest uncertainty estimates, yet they remained confined to journals. We founded this platform to close that gap. Our approach draws on decades of combined experience in quantitative finance and applied statistics, translating complex nonparametric methods into frameworks that practitioners can actually use. We ask careful questions about model assumptions before reaching for convenient answers, and we expect our learners to do the same. That skeptical, rigorous habit of mind is at the heart of everything we build here.
The People Behind the Methods and the Thinking
Our core team brings together academic researchers, former institutional analysts, and applied statisticians who have spent careers questioning model assumptions and building more honest tools for measuring financial uncertainty. Each member contributes a distinct perspective — from pure statistical theory to hands-on market risk practice — and that productive tension shows up in everything we produce.
-
Dr. Miriam Osei, Lead Research Director
Nonparametric methods and equity risk premium research
Miriam leads our core research agenda, specialising in distribution-free estimation frameworks for equity and credit risk premiums. Her academic background spans econometrics and mathematical statistics, and she spent a significant portion of her career developing internal risk models for institutional asset managers before joining the platform. She is known for asking the uncomfortable question before the meeting ends.
-
Carlos Mendez, Platform Research Lead
Applied methodology development and practitioner frameworks
Carlos bridges the gap between theoretical statistical research and the practical concerns of analysts working with financial data daily. He designs the applied frameworks that translate academic nonparametric methods into structured, repeatable analytical processes. His background includes time in both sell-side research and independent quantitative consulting across Australian and international markets.
-
Dr. Priya Nair, Credit Risk Specialist
Nonparametric credit risk premium estimation
Priya brings focused expertise in applying distribution-free methods to credit risk premium estimation, an area where parametric assumptions have historically caused the most trouble during market stress periods. She has written extensively on the limitations of standard credit spread models and the alternatives that empirical distribution methods offer to researchers willing to do more careful work.
-
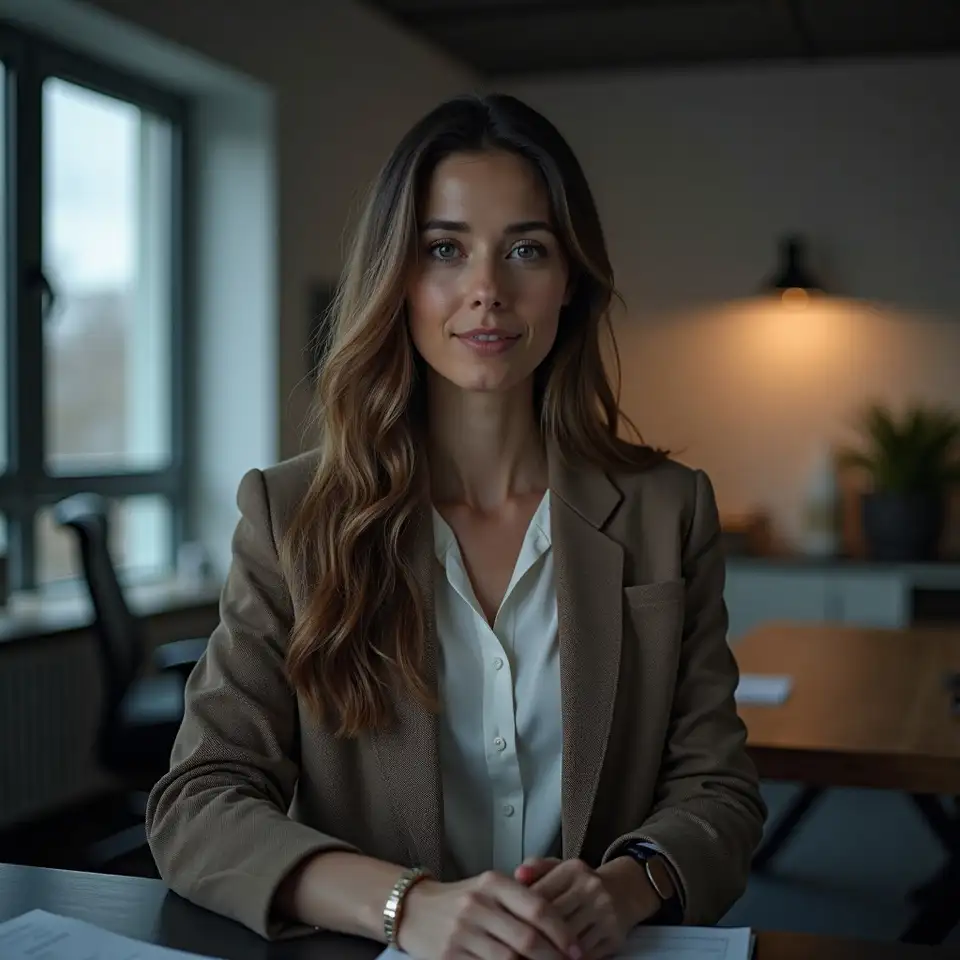
Dr. Anika Holm, Econometrics Research Fellow
Rank-based inference and distributional analysis
Anika specialises in rank-based and sign-based statistical inference methods, exploring their application to financial time series where standard assumptions around normality and independence routinely fail. Her fellowship research examines how these methods perform across different market regimes, providing a more cautious and honest picture of uncertainty than conventional parametric approaches typically deliver.
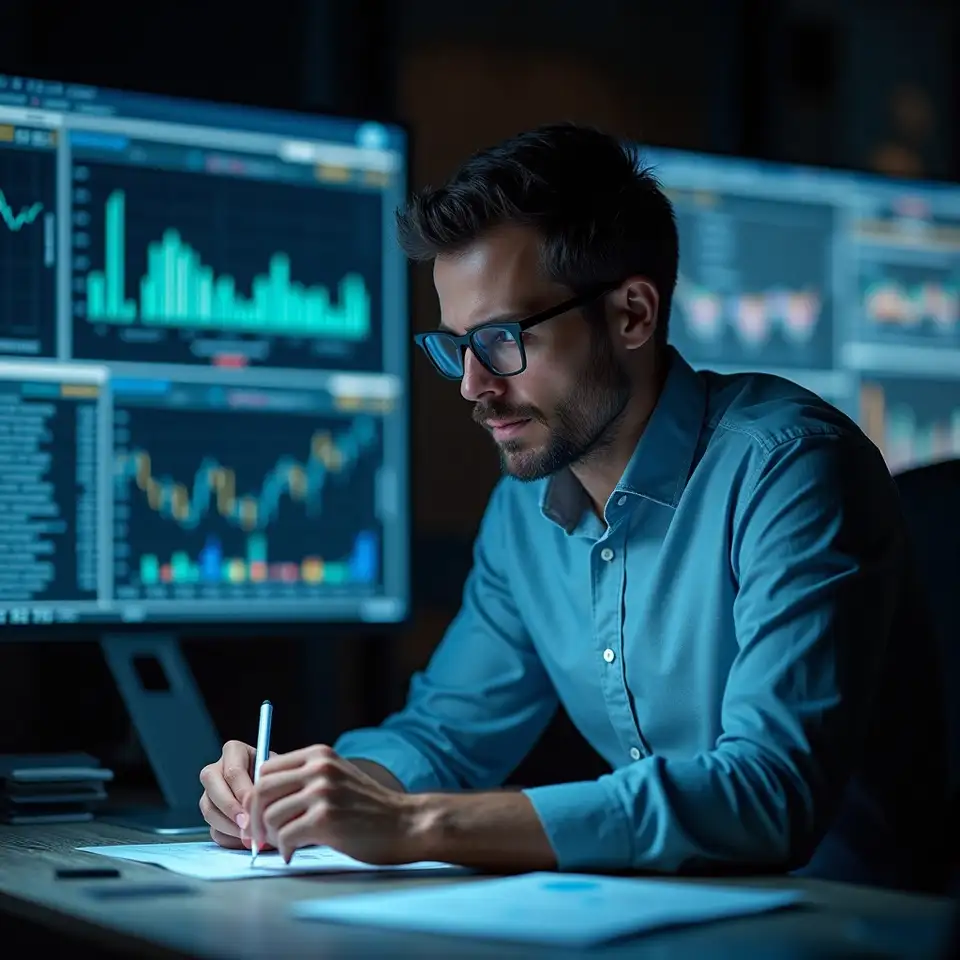
Dr. James Hartwell, Senior Quantitative Analyst
Volatility risk premium modelling and inference
James focuses on the estimation of volatility risk premiums using kernel-based and rank-based methods that sidestep the distributional assumptions conventional models impose. He holds a doctorate in applied probability and has contributed to peer-reviewed literature on robust inference. His explanations of complex inference problems are, colleagues note, unusually clear.
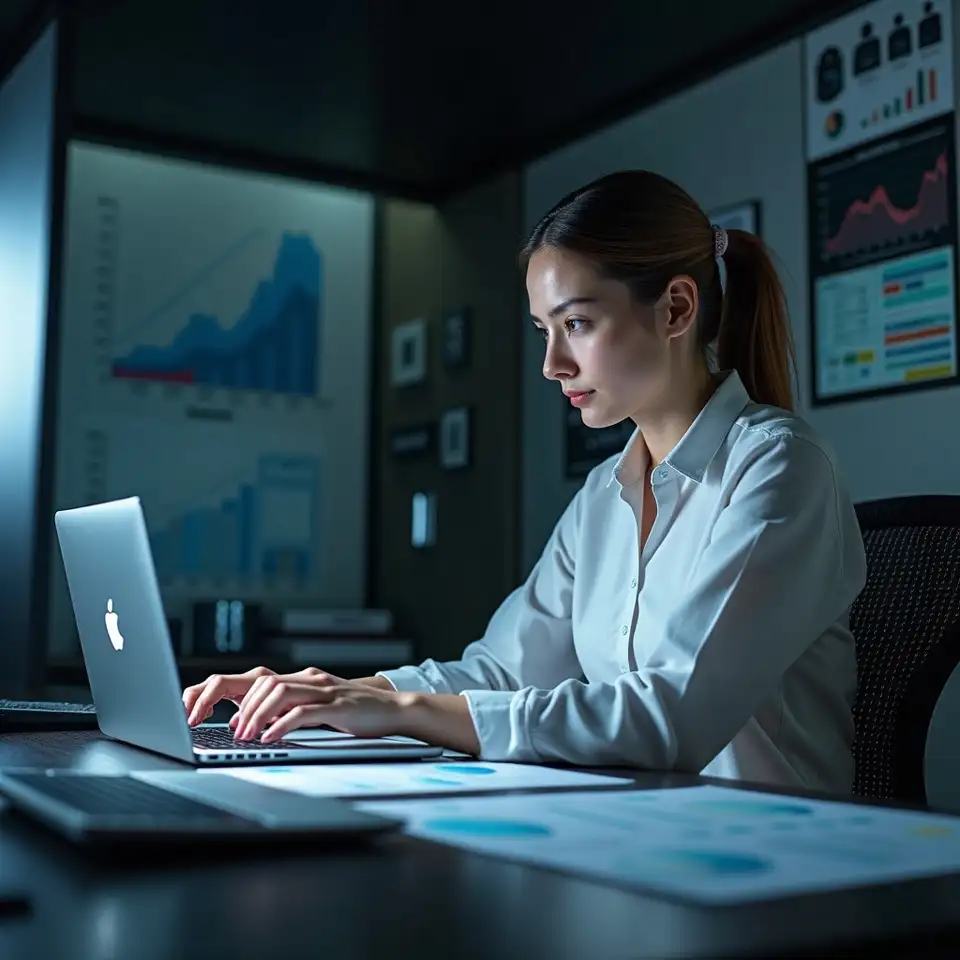
Dr. Yuki Tanaka, Statistical Methods Advisor
Bootstrap resampling and robust statistical inference
Yuki advises on the theoretical foundations underpinning our resampling frameworks, with particular depth in bootstrap and permutation-based confidence construction. Her research examines how nonparametric techniques behave under real-world data conditions — heavy tails, autocorrelation, and structural breaks — rather than textbook assumptions. She treats every dataset as a suspect until proven otherwise.
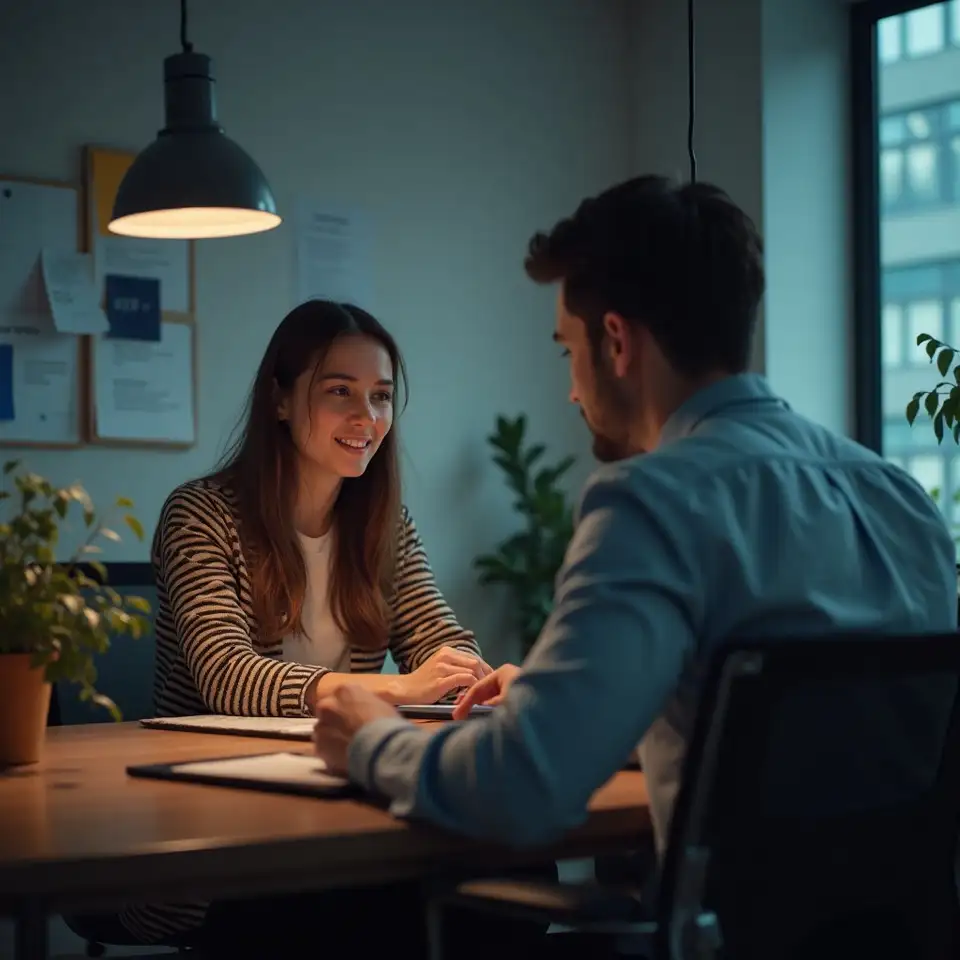
Thomas Brauer, Academic Partnerships Coordinator
Research collaboration and methodology review
Thomas manages the platform's relationships with academic institutions and oversees the peer review process for our published methodology documentation. With a background in financial economics and a keen eye for methodological rigour, he ensures that every framework we present has been stress-tested against both theoretical critique and real data. He believes good methodology should be defensible at a seminar.
What Guides Our Work
Eight principles that shape how we approach every method, every analysis, and every explanation we produce
Methodological Honesty
We do not reach for the convenient parametric assumption when the data does not
support it. Every framework we develop is built around an explicit acknowledgment of
what we do and do not know about the underlying distribution of returns, premiums,
or risks. Intellectual honesty about model limitations is, we think, the starting
point for serious quantitative work.
Rigorous Skepticism
We treat every model assumption as a hypothesis rather than a given. Before accepting a standard approach to risk premium estimation, our team asks whether the distributional conditions that justify it are actually present in the data. That habit of questioning familiar tools is the specific discipline we try to cultivate across all of our analytical work.
Practical Relevance
Theoretical elegance matters, but a method that cannot be applied to real financial data under real market conditions is of limited use to practitioners. We design our nonparametric frameworks with implementation in mind, testing them against empirical data that includes the heavy tails, regime changes, and autocorrelation structures that markets actually produce.
Transparent Reasoning
Every analytical step we take is documented and defensible. We show our working —
including the assumptions we could not avoid — so that any researcher or
practitioner following our methods can identify exactly where their own judgment
needs to be applied. Opacity in quantitative finance has a track record we find
unpersuasive.
Continuous Refinement
Statistical methodology does not stand still, and neither do we. Our research team
actively monitors developments in nonparametric inference, robust estimation, and
empirical finance, incorporating improvements into our frameworks when the evidence
supports them. We regard our current methods as the best available starting point,
not the final word.
Inclusive Access
Advanced statistical methods for risk premium estimation have historically been the Flentiollour of well-resourced research departments. We believe that a broader community of analysts, researchers, and practitioners benefits when these tools are explained clearly and made genuinely accessible — without sacrificing the rigour that makes them worth using in the first place.
Evidence-Driven Decisions
Our analytical positions are formed by what the data shows, not by what a particular
model predicts it should show. Nonparametric approaches are, at their core, a
commitment to letting empirical distributions speak rather than imposing prior
assumptions upon them. That same orientation toward evidence shapes every
methodological choice our team makes.
Collaborative Inquiry
The best nonparametric methods we know emerged from productive disagreement between
researchers with different training and different priors. We maintain that
collaborative, questioning culture inside our team, and we extend it outward through
our partnerships with academic institutions and our engagement with the broader
quantitative research community.
Recognition Received
2023
APRA Research
Quantitative Research Excellence Award
Recognised for outstanding contribution to applied nonparametric methods in financial risk research, as assessed by a panel of academic and industry reviewers.
2022
FinAnalytics Institute
Best Financial Methodology Publication
Our peer-reviewed framework for distribution-free equity risk premium estimation was cited as a leading contribution to robust empirical finance literature.
2024
AusQuant Forum
Academic Partnership of the Year
Awarded in recognition of sustained and productive collaboration with university research departments advancing nonparametric statistical inference in finance.
2021
RiskPro Australia
Practitioner Impact Recognition
Acknowledged for translating complex distribution-free statistical techniques into frameworks with demonstrable relevance to institutional risk analysis practice.
How We Got Here
A sequence of deliberate steps, not a straight line
2017
Platform Founded by Researchers
A small group of quantitative finance researchers and applied statisticians founded the platform with a specific purpose: to develop and document distribution-free methods for estimating risk premiums that did not depend on assumptions the data rarely supported. The founding team brought experience from academic econometrics and institutional risk analysis.
Founding
Research
2019
First Methodology Framework Published
Our inaugural nonparametric framework for equity risk premium estimation was completed, peer-reviewed, and made available to a growing community of practitioners and researchers. The framework drew on kernel density estimation and bootstrap resampling methods, offering an alternative to standard parametric approaches without sacrificing analytical rigour.
Methodology
Publication
2021
Credit Risk Methods Introduced
The research team expanded its scope to include nonparametric approaches to credit risk premium estimation — an area where distributional assumptions embedded in conventional models had contributed to significant mismeasurement during previous stress periods. New frameworks addressing heavy-tailed distributions and structural breaks were developed and documented.
Credit Risk
Expansion
2023
Academic Partnerships Established
Formal research partnerships with several Australian university departments deepened the platform's connection to the academic community. These collaborations introduced a structured peer-review process for all new methodology documentation and brought additional expertise in rank-based inference and robust statistical estimation into the team's work.
Partnerships
Academia
2025
Volatility Premium Research Expanded
Our volatility risk premium research strand reached a significant milestone, producing a comprehensive suite of distribution-free estimation tools designed for use across different market regimes. The work addressed the particular challenge of inference under autocorrelation and non-stationarity — conditions that standard volatility models tend to handle poorly.
Volatility
Milestone
Our founding to now